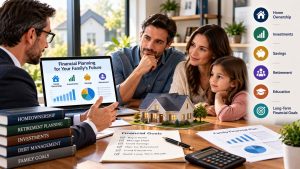
Buying a home is one of the largest financial decisions many families make, but it rarely exists in isolation. A mortgage affects monthly cash flow, a down payment can change available savings, and housing costs can influence how much a household can put toward retirement, investments, education, or other long-term goals.
That does not mean homeownership is simply a financial calculation. A home can provide stability, flexibility, and a place for a family to build its life. The important consideration is how the decision fits within the household’s broader financial picture.
For families working through several competing priorities, professional guidance can help bring those decisions together. Businesses such as Financial Advisor Leads operate on the client-acquisition side of financial services, but the underlying need for clear financial planning begins with understanding how individual decisions affect the larger picture.
Start With the Full Financial Picture
A home purchase can look affordable when viewed only through the lens of a mortgage payment.
The broader picture includes the down payment, closing costs, property taxes, insurance, maintenance, utilities, potential renovations, and other ongoing expenses. It also includes the opportunity cost of using savings for a home rather than another financial goal.
This is why families may benefit from looking at the decision alongside their existing income, expenses, debts, savings, and investment plans.
The Financial Consumer Agency of Canada recommends considering the full costs of buying a home and using a budget to understand what can realistically be afforded. Its home-buying guidance also highlights the importance of considering mortgage payments, property taxes, heating costs, and other debts when assessing affordability. Financial Consumer Agency of Canada: Buying a Home
The practical lesson is straightforward: the purchase price is only one part of the financial commitment.
Consider How a Mortgage Affects Cash Flow
A mortgage can become one of the largest recurring expenses in a household budget.
That can influence decisions that may appear unrelated to housing. A larger monthly commitment could affect how much a family is able to save for retirement, contribute toward investments, build an emergency fund, or spend on other priorities.
The reverse can also happen. A household with manageable housing costs may have greater flexibility to direct surplus cash toward other goals.
The question is therefore not simply whether a household can qualify for a mortgage. It is whether the resulting financial commitment fits comfortably within the family’s broader plans.
This distinction matters because lender approval and personal financial comfort are not necessarily the same thing.
Balance Homeownership With Other Goals
Families rarely have only one financial objective.
A couple may be saving for a home while also contributing to retirement accounts. Parents may be thinking about education costs for their children. Someone may be carrying student debt or a car loan while trying to build an emergency reserve.
Putting all available savings toward a home can make sense for some households, while maintaining more flexibility may be important for others.
There is no universal allocation that works for everyone.
Instead, families can start by identifying their priorities and considering how much time they have to achieve each one. A short-term home purchase goal may need to be treated differently from a retirement objective that is decades away.
This is where financial planning becomes useful: it creates a framework for comparing competing goals rather than evaluating each decision separately.
Think Carefully About Debt
Homeownership often involves taking on substantial long-term debt.
That debt can be manageable when it fits within household cash flow, but it can also reduce flexibility if a family’s income changes or other major expenses arise.
Other forms of borrowing matter too. Credit cards, student loans, personal loans, vehicle financing, and lines of credit can all compete with mortgage payments for space in a household budget.
A family considering a home purchase may therefore want to understand its entire debt position rather than focusing exclusively on the mortgage.
Debt also interacts with future choices. A household that prioritizes mortgage repayment may have a different investment or retirement strategy from one that places greater emphasis on maintaining liquid savings.
The right approach depends on the family’s circumstances, goals, time horizon, and tolerance for financial risk.
Keep Retirement in the Conversation
Retirement can seem distant when a family is focused on buying its first home, raising children, or managing current expenses.
However, housing decisions can influence retirement planning over many years.
A mortgage that extends close to retirement may affect future cash flow. Conversely, paying down housing debt earlier could change the amount of income a household needs later.
The home itself can also become part of a family’s long-term financial picture. Some people may expect to remain in the property throughout retirement, while others may eventually move, downsize, or relocate.
None of these possibilities should be treated as guaranteed outcomes.
Instead, they are scenarios worth considering when developing a long-term plan.
The goal is not necessarily to prioritize retirement over homeownership or vice versa. It is to understand how today’s housing decision may influence tomorrow’s choices.
Think About Investments Alongside the Home
For many families, a primary residence becomes a significant part of their overall net worth.
That can create a concentration of wealth in one physical asset.
Homeownership may provide long-term value, but a residence does not function exactly like a diversified investment portfolio. It cannot necessarily be sold quickly without affecting where the family lives, and its future value is not guaranteed.
This is one reason broader financial planning can be useful.
A household can consider how home equity, savings, retirement accounts, investments, and other assets fit together rather than viewing the home as the entire financial strategy.
The objective is not to make a judgment about whether real estate or financial investments are preferable. It is to recognize that different assets can serve different purposes.
Plan for Major Life Changes
Financial plans should leave room for life to change.
A family may experience a career transition, a new child, a change in income, an inheritance, a business opportunity, or an unexpected expense. A home purchase that seemed comfortable under one set of circumstances may require reconsideration later.
This is another reason to avoid building a financial plan around a single assumption.
Instead, families can consider how their finances might respond if income changes, expenses increase, or their priorities shift.
For example, someone planning to start a business may need more accessible savings than they did previously. A family expecting a significant career change may want to reassess its debt commitments. Someone approaching retirement may have different priorities from a household that is just entering the workforce.
Financial planning is most useful when it can adapt to those changes.
Know When Several Decisions Are Connected
The complexity often begins when several major financial decisions happen at the same time.
Imagine a family purchasing a home while also considering a career change, planning for children, paying down existing debt, and trying to maintain retirement contributions.
Each decision affects the others.
Reducing debt may require more monthly cash flow. A larger down payment may reduce the mortgage but leave less liquid savings. Increasing retirement contributions may reduce the amount available for other short-term goals.
There may not be one obviously correct answer.
Instead, the family needs to understand the trade-offs and decide which priorities matter most.
That is where professional financial planning can provide structure. Rather than treating the mortgage, investments, savings, and retirement plan as separate conversations, a broader approach can examine how they interact.
Financial Guidance Can Support Better Coordination
Professional financial planning is not about telling every household to make the same choices.
It can help organize information, clarify goals, compare scenarios, and identify areas where one financial decision could affect another.
For people who are buying a home, this may mean considering the purchase alongside debt, savings, investments, insurance, retirement planning, and family objectives.
For advisors and financial planning firms, digital lead generation for financial professionals can help create opportunities to connect with people who are looking for guidance around these kinds of decisions, but the value of the eventual relationship depends on the quality of the planning conversation.
The most useful conversations often begin with the family’s priorities rather than with a particular financial product.
Build a Plan Around the Life, Not Just the House
A home can be an important part of a family’s financial story, but it is rarely the entire story.
The mortgage, down payment, debt, investments, retirement savings, insurance, income, and future goals all exist within the same household financial system. Changing one part can influence the others.
That is why major homeownership decisions deserve to be considered in context.
A thoughtful financial plan does not have to predict every future event. It should instead give a family a clearer way to understand its current position, weigh competing priorities, and revisit decisions as circumstances change.
Homeownership can then be treated not as a financial destination, but as one part of a broader plan for building the life and future a family wants.
